PepsiCo Faces Increasing Pressure from Investors Amid Declining Margins
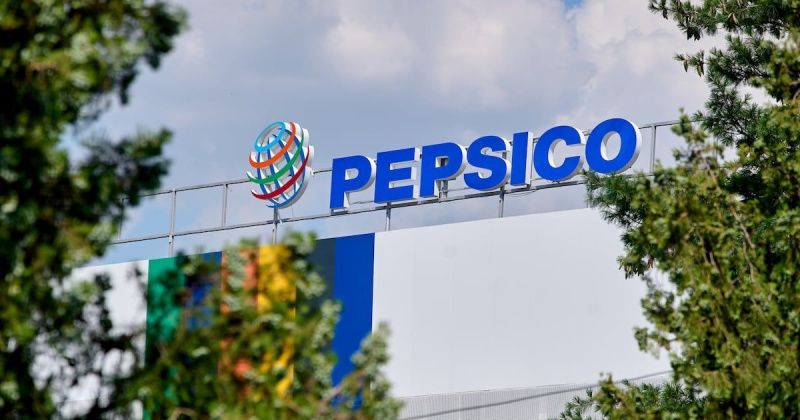
PepsiCo, the American multinational food, snack, and beverage corporation, is experiencing heightened scrutiny as it fails to meet growth expectations set by investors. The company's North American business is particularly affected, with a consistent drop in product volumes attributed to rising food and drink inflation, heightened competition, and the influence of GLP-1 weight-loss drugs.
Despite PepsiCo's efforts to implement drastic measures aimed at improving performance, such as record productivity savings and a 15% price reduction on its flagship products like Lay’s and Doritos, these strategies have not yet resulted in significant improvements in its financial outcomes. The company has also faced pressure from Elliott Investment Management, which acquired a roughly $4 billion stake a year ago.
According to recent reports, PepsiCo's core operating margin fell to 16.3% in the first half of the year, reflecting a decrease of 15 basis points year-on-year. This points to a significant divergence from its target of increasing margins by 100 basis points over a span of three years. Moreover, the company's stock price has seen a near 12% decline this year, with a 16% drop since Elliott's investment.
Analysts, including Stephanie Link from Hightower Advisors, note the lack of a focused recovery strategy amid ongoing changes. This has been complicated by the rising influence of GLP-1s. In response, PepsiCo has begun to reintroduce higher prices on certain U.S. chips and beverages, indicating a shift from the earlier strategy of price reductions meant to boost volumes.
The enduring question is whether PepsiCo can swiftly turn around its North American snacks business to appease its investors, with a focus on adapting to a market increasingly shaped by health-conscious consumers and the impact of new pharmaceutical trends.