Coca-Cola's Earnings and Revenue Trends Amid Investor Interest
Coca-Cola, the world's largest beverage producer, has recently drawn significant attention from investors, as evidenced by its frequent searches on Zacks.com. Over the past month, Coca-Cola's shares have experienced a return of -0.1%, which contrasts with the Zacks S&P 500 composite's increase of +5.4%. The soft drinks industry, to which Coca-Cola belongs, saw a modest gain of 0.2% in the same period.
Earnings Estimate Revisions
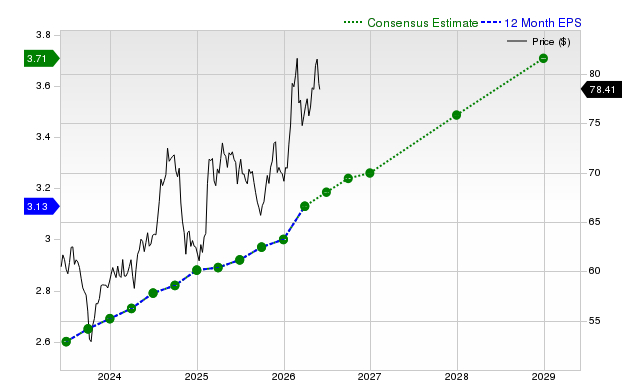
Analysts have revised their projections for Coca-Cola's future earnings. For the current quarter, Coca-Cola is expected to post earnings of $0.93 per share, marking a 6.9% increase from the same quarter last year. The Zacks Consensus Estimate for this quarter has adjusted by -0.7% over the past 30 days. For the current fiscal year, the consensus earnings estimate is $3.26, an 8.7% increase from the previous year. This estimate has remained unchanged in the last month.
Looking ahead to the next fiscal year, the consensus earnings estimate sits at $3.49, which indicates a 7% increase compared to the expected results for this fiscal year. Notably, the estimate has shifted by +0.1% over the past month. Based on the recent changes in the consensus estimate and other related factors, Coca-Cola holds a Zacks Rank of #2 (Buy).
Revenue Growth Forecast
The consensus sales estimate for Coca-Cola's current quarter is $13.05 billion, indicating a 4.2% year-over-year rise. For the current fiscal year, the revenue is projected to reach $49.33 billion, reflecting a 3% increase, while the next fiscal year is estimated at $50.3 billion, a 2% rise.
Recent Performance and Valuation
In the last reported quarter, Coca-Cola achieved revenues of $12.47 billion, a 12.1% increase from the previous year, and an EPS of $0.86, up from $0.73. This exceeded the Zacks Consensus Estimate of $12.3 billion, with a revenue surprise of +1.37% and an EPS surprise of +6.17%. Over the last four quarters, Coca-Cola has consistently surpassed consensus EPS estimates, although it only topped revenue estimates once.
The company's valuation, as assessed by the Zacks Value Style Score, is graded as D, suggesting it trades at a premium compared to its peers.